Investment-Grade Credit Spreads: 0.89% as of October 2026 (monthly average)
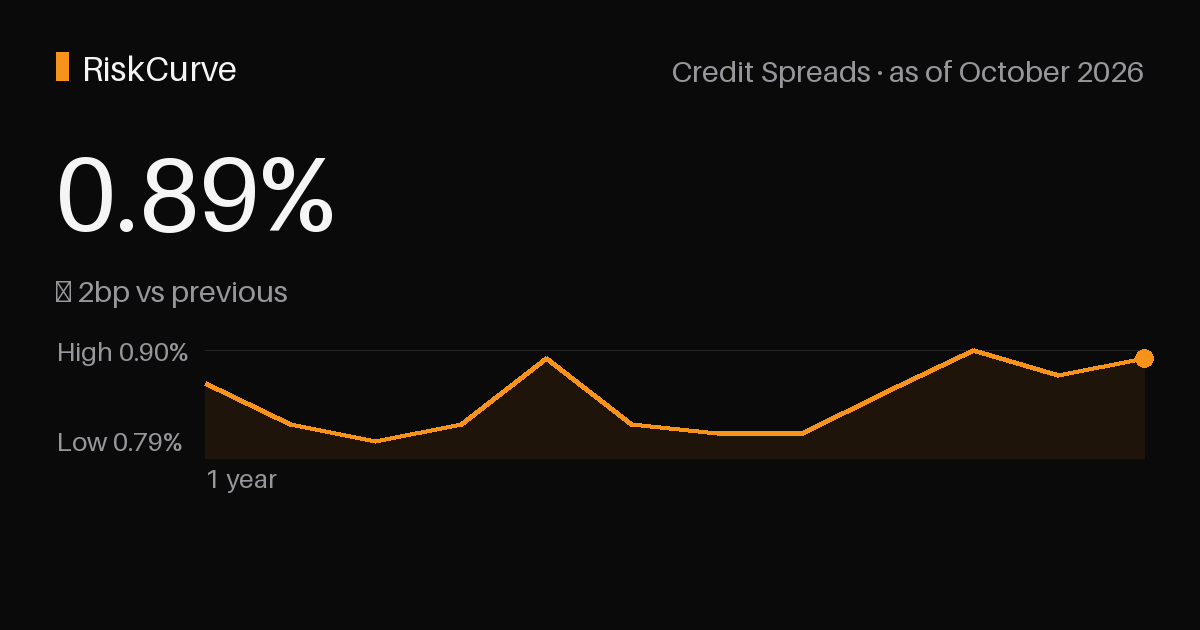
Our investment-grade credit spread proxy is 0.89% as of October 2026 (monthly average), +0.02pp versus the previous reading. It is a proxy, not an index quote: we take the High Quality Market 10-year corporate spot rate published by the U.S. Treasury (FRED series HQMCB10YR) and subtract the 10-year Treasury yield (GS10), matched to the same month.
A credit spread is the purest market price of default risk. Treasuries are treated as default-free, so anything a corporate bond pays above their yield is compensation for the chance the borrower fails to pay. Because the HQM curve is published monthly and covers high-quality issuers, this proxy tracks investment-grade risk with a monthly cadence and a modest lag.
Spreads widen when investors get nervous — recessions, credit events, funding shocks — and compress when they feel confident. The warning sign is rarely a high level on its own but a rapid widening, which has historically preceded equity drawdowns and tighter lending conditions. We pair the proxy with two independent stress measures: the Chicago Fed credit subindex (weekly) and the St. Louis Fed Financial Stress Index (weekly), so a widening proxy can be cross-checked against a broader read on financial conditions.
The short-term spread measures corporate funding stress rather than long-term default risk: it is the rate AA nonfinancial firms pay on 30-day commercial paper over the 4-week T-bill, so it spikes when short-term funding dries up — 2008 and March 2020 — while the monthly HQM measure tracks longer-term investment-grade risk. Both legs come from the Federal Reserve Board’s H.15 release and are paired on the same day only, so the two measures never borrow each other’s date.
For portfolio construction, credit spreads set the compensation for taking corporate risk and inform the choice between credit and duration. We track credit and financial stress on the RiskCurve dashboard.
It is 0.02pp higher than a month ago (Sep 2026).
It is above the 0.84% average of the period we track, which has run from 0.79% (Jan 2026) to 0.90% (Aug 2026) — the highest since Aug 2026.
IG corporate spread proxy (10Y corporate − 10Y Treasury) — recent values
| Date | Value |
|---|---|
| Oct 2026 | 0.89% |
| Sep 2026 | 0.87% |
| Aug 2026 | 0.90% |
| Jul 2026 | 0.85% |
| Jun 2026 | 0.80% |
| May 2026 | 0.80% |
| Apr 2026 | 0.81% |
| Mar 2026 | 0.89% |
| Feb 2026 | 0.81% |
| Jan 2026 | 0.79% |
Values as published by the source. Macro series are revised after first release; this table shows the most recent vintage. Saved dataset: JSON.
Related credit & financial-stress measures
| Measure | Latest | As of |
|---|---|---|
| Chicago Fed credit subindex (NFCICREDIT) | -0.01 | Week of November 6, 2026 |
| St. Louis Fed Financial Stress Index (STLFSI4) | -0.49 | Week of November 6, 2026 |
These are separate series, published on their own cadence, and are shown for cross-reference rather than combined into a single score.