VIX: 22.91 as of Nov 16
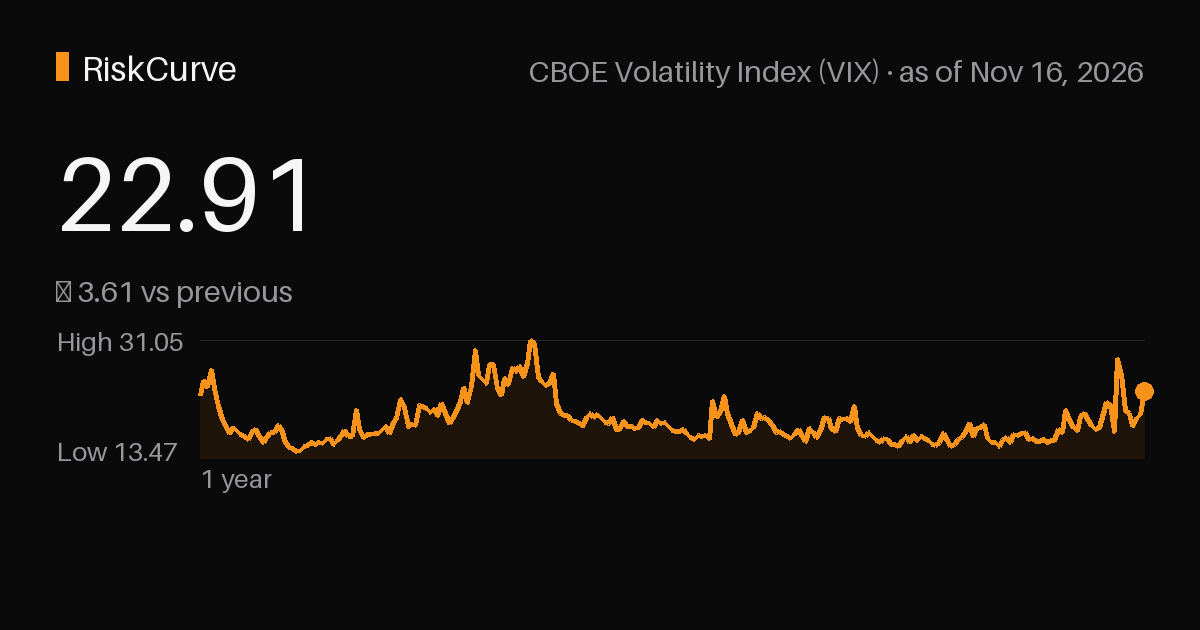
The CBOE Volatility Index, universally known as the VIX, measures the market’s expectation of 30-day volatility in the S&P 500, implied from the prices of index options. It is currently 22.91 as of November 16, 2026, +3.61pts versus the previous close.
Unlike most indicators here, the VIX is not a level on an underlying asset — it is a price for risk itself. When investors are anxious they pay up for downside protection, option premiums rise, and the VIX climbs. When they are complacent, protection is cheap and the VIX sits in the low teens.
The index is expressed in annualised percentage points, so a reading of 20 implies the market expects roughly a 20% annualised move in the S&P 500 over the next month — about 5.8% in either direction over 30 days. Levels above 30 signal acute stress, above 40 usually mark crisis conditions, and below 15 signals deep complacency. Spikes in the VIX are typically sharp and fade quickly; low readings can persist for a long time.
For investors the VIX is both a risk gauge and a tradable instrument, though volatility products carry well-documented structural decay. We track the VIX alongside credit and financial-stress measures on the RiskCurve dashboard.
It is 2.92pts higher than a month ago (Oct 16, 2026), and 3.08pts higher than a year ago (Nov 14, 2025).
It is above the 18.11 average of the period we track, which has run from 13.47 (Dec 24, 2025) to 31.05 (Mar 27, 2026) — the highest since Nov 06, 2026.
CBOE Volatility Index (VIX) — recent values
| Date | Value |
|---|---|
| Nov 16, 2026 | 22.91 |
| Nov 13, 2026 | 19.30 |
| Nov 12, 2026 | 18.70 |
| Nov 11, 2026 | 17.49 |
| Nov 10, 2026 | 19.46 |
| Nov 09, 2026 | 19.92 |
| Nov 06, 2026 | 25.64 |
| Nov 05, 2026 | 28.18 |
| Nov 04, 2026 | 16.61 |
| Nov 03, 2026 | 20.83 |
Values as published by the source. Macro series are revised after first release; this table shows the most recent vintage. Saved dataset: JSON.