2-Year Treasury Yield: 4.80% as of Nov 17
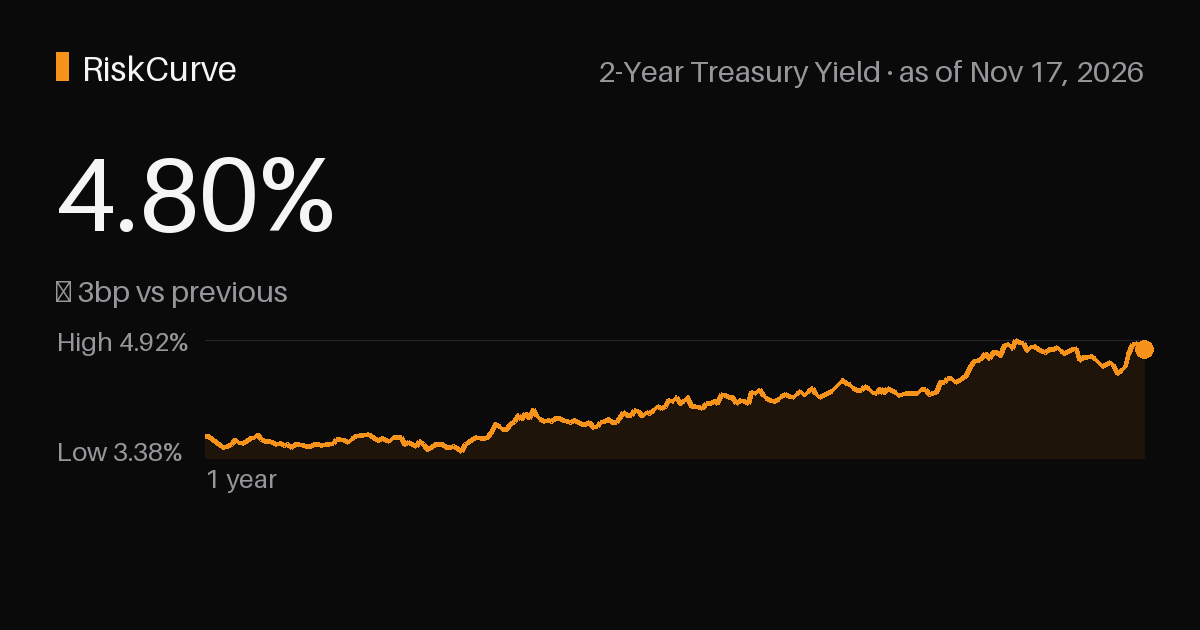
The 2-year Treasury yield is the rate on US government debt maturing in two years. It is currently 4.80% as of November 17, 2026, −0.03pp versus the prior session.
More than any other maturity, the 2-year tracks the market’s expectation for Federal Reserve policy. Because the Fed sets only the overnight rate, a two-year bond spans roughly the horizon over which the market prices the next several policy moves. When traders expect rate cuts, the 2-year falls quickly; when they expect hikes or a “higher for longer” stance, it rises.
That sensitivity makes the 2-year the cleanest read on the policy path. The gap between the 2-year yield and the current fed funds rate is effectively a market forecast of where the committee is heading. The 2-year also sets the short end of the curve used in the 10Y–2Y spread, the most cited recession indicator in macro.
For investors, the 2-year drives the front end of duration positioning and is the instrument of choice for expressing a view on Fed policy without taking long-duration risk. We track its level daily alongside the full Treasury curve.
It is 0.06pp higher than a month ago (Oct 16, 2026), and 1.20pp higher than a year ago (Nov 17, 2025).
It is above the 4.01% average of the period we track, which has run from 3.38% (Feb 27, 2026) to 4.92% (Sep 28, 2026).
2-Year Treasury Yield — recent values
| Date | Value |
|---|---|
| Nov 17, 2026 | 4.80% |
| Nov 16, 2026 | 4.83% |
| Nov 13, 2026 | 4.88% |
| Nov 12, 2026 | 4.86% |
| Nov 10, 2026 | 4.73% |
| Nov 09, 2026 | 4.56% |
| Nov 06, 2026 | 4.51% |
| Nov 05, 2026 | 4.46% |
| Nov 04, 2026 | 4.58% |
| Nov 03, 2026 | 4.61% |
Values as published by the source. Macro series are revised after first release; this table shows the most recent vintage. Saved dataset: JSON.